Most families and professionals shopping for term coverage start with one number: the monthly premium. It's a reasonable place to begin, but a cheap quote can hide gaps that only surface years later, when your health changes or you want to switch carriers.
The right term life insurance questions to ask reveal what a policy will actually do over 10, 20, or 30 years. The list below covers renewal rules, conversion rights, premium stability, early-year exclusions, underwriting, riders, insurer strength, and the administrative details that often trip up beneficiaries.
Each question includes a real-world scenario and a clear action step, so you can apply it to your own quotes right away. Expect a practical, straightforward walkthrough with no jargon left unexplained.
Table of Contents
- 1. Is the policy guaranteed renewable, and what happens when the term ends?
- 2. Does the policy include a conversion option, and until what age can I use it?
- 3. How long is the level premium period, and can my premium change during the term?
- 4. What is the contestability period, and what exclusions apply in the first two years?
- 5. Do I need a medical exam, and how does accelerated underwriting work?
- 6. Which riders are available, and what do they add to the cost?
- 7. How does the insurer handle claims, and what are its financial strength ratings?
- 8. What are the free-look and grace periods, and how do I update my beneficiaries?
- 8 Key Term Life Insurance Questions Compared
- Ask Smart, Buy With Confidence
1. Is the policy guaranteed renewable, and what happens when the term ends?
Every term policy eventually expires, and that is where many buyers get caught off guard. One of the most important term life insurance questions to ask is whether you can keep your coverage afterward without proving your health again.
Guaranteed renewability means the insurer must renew your policy when the term ends, regardless of changes in your health. The catch is price. Renewal premiums are based on your current age and often run several times the original level rate.
Consider a 35-year-old with a 20-year level term policy. At 55, the guaranteed renewal could cost several times the original premium, so the smarter move is to buy a new policy or convert while still insurable.
What to Do Before the Term Ends
- Request the exact renewal premium schedule in writing, not just the guarantee language.
- Compare that renewal cost against a fresh term policy quoted at the same age.
- Set a calendar reminder 12 months before expiration to review your options.
Guaranteed renewability protects your access to coverage, not your budget. Get the renewal numbers before you need them.
2. Does the policy include a conversion option, and until what age can I use it?
A conversion option lets you switch a term policy into a permanent one, such as whole or universal life, without a new medical exam. Insurers like MassMutual and Lincoln Financial offer this feature, but the deadline often arrives years before the term ends.
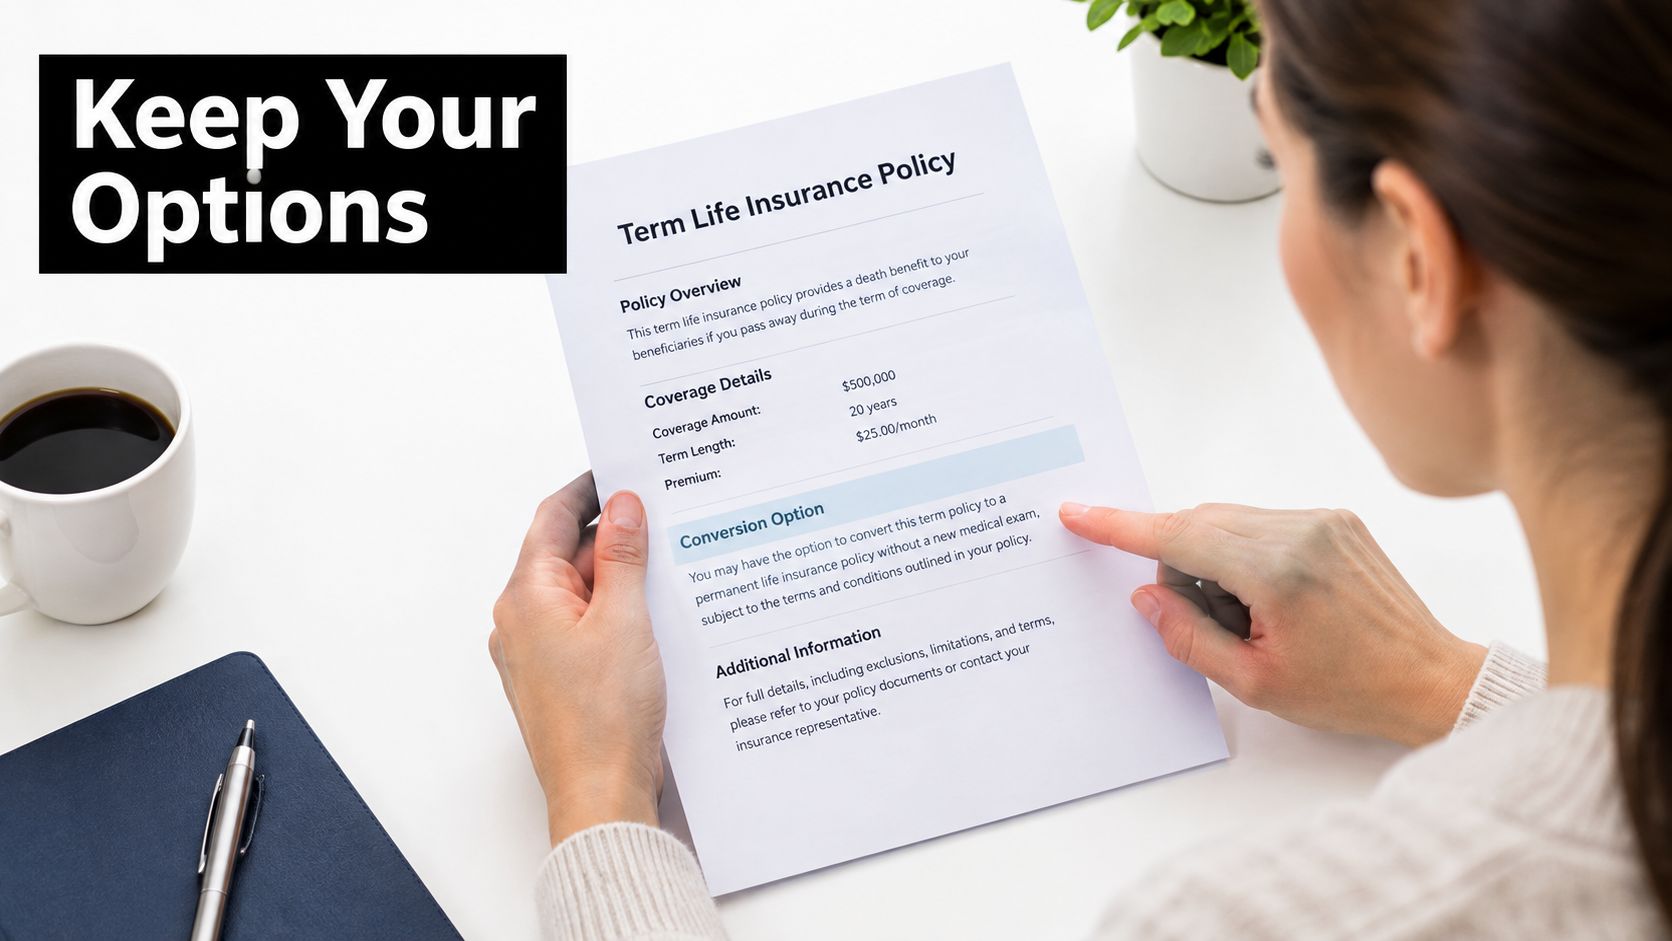
Conversion matters most when your health changes. A diagnosis in your 40s could make a fresh application expensive or impossible, but a conversion right lets you keep coverage without new underwriting.
Consider a business professional with a 30-year term policy who is diagnosed with a serious condition at 45. Converting to permanent coverage keeps the death benefit in place to fund a partnership buyout.
What to Do Before the Deadline
- Ask for the exact conversion deadline and whether it is tied to your age or policy year.
- Request a sample premium quote for a converted policy and compare it with a new application.
- Confirm whether you can convert the full face amount or only part of it.
A conversion right is only valuable if you use it on time. Learn the cutoff date while you are still healthy.
3. How long is the level premium period, and can my premium change during the term?
Among the term life insurance questions to ask, this one often gets the least attention, yet it determines how predictable your bills will be for years. A low monthly quote means little if the rate can shift before your biggest obligations are paid off.
Level term policies lock your premium for a set period, commonly 10, 15, 20, or 30 years. Once that window closes, the premium typically resets to a much higher rate based on your age at that point.
Ask whether the quoted price stays level for the full term or only for the first few years. Some policies advertise an attractive starting rate, and buyers often discover the adjustment only after signing.
Consider a newly married couple who buys a 20-year level term policy with a $500,000 face amount. Their payment stays the same while they pay off a home and raise young children, so their budget holds steady through the years they need it most.
How to Lock In Your Budget
- Confirm the level period length in the policy contract, not just the sales summary.
- Match the term to your largest obligation, such as a mortgage or your children's education costs.
- Verify in writing that the insurer cannot raise the premium during the level period.
A premium is only predictable if the guarantee covers the years you actually need protection.
4. What is the contestability period, and what exclusions apply in the first two years?
The first two years of a policy are when insurers look most closely at your file. Among the term life insurance questions to ask, this one can decide whether your family gets paid quickly or waits months for answers.
During the contestability period, the insurer can investigate a claim and deny it if it finds material misstatements on your application. A suicide exclusion usually applies in this window too, often for the first two years.
A professional who left out a recent doctor visit on the application files a claim in year one. The insurer reviews the file, and payment is delayed while the family waits for answers.
What to Ask Your Agent
- How long is the contestability period in this specific policy?
- How long does the suicide exclusion last, and what is paid afterward?
- How does the insurer handle claims filed within the first two years?
Keep copies of your application, medical records, and insurer correspondence. Learn more about how the contestability period works.
Accurate answers on day one are what keep a claim payable on day 400.
5. Do I need a medical exam, and how does accelerated underwriting work?
Among the term life insurance questions to ask, this one affects both your timeline and your premium. Traditional underwriting usually requires a paramedical exam with blood and urine samples, which can take weeks to schedule and review.
Accelerated underwriting skips that step. Insurers review prescription history, driving records, and credit-based data to reach a decision, and some applicants get approved within minutes.
A healthy 32-year-old applying online for $1 million in coverage might receive an instant decision with no exam and start coverage the same week.
What to Check Before You Apply
- Ask whether the no-exam offer is priced the same as a fully underwritten policy.
- Confirm whether you qualify for an exam waiver at your desired coverage level.
- Gather accurate medication names, dosages, and medical history dates before you submit.
Some insurers reserve their lowest rates for applicants who complete the exam, so a fast approval isn't always the cheapest option. Compare both paths before you accept.
A quick decision is convenient, but the best premium often goes to applicants whose verified health records look clean.
6. Which riders are available, and what do they add to the cost?
Riders are optional add-ons that reshape a base term policy. They are easy to overlook among the term life insurance questions to ask, but many buyers accept whatever a quote includes without checking what each feature costs.
Common options include accelerated death benefit riders, waiver of premium riders, child term riders, and term conversion riders. Some are included at no charge, while others add to your monthly premium. Learn more about how riders work before you compare quotes.
A couple who adds a child term rider when their first child is born, for example, pays a small extra premium to cover the child until the rider ends. That gives them affordable protection for a need that arrived after the original policy was written.
How to Price Riders Wisely
- Request quotes with and without each rider to see its exact cost.
- Read the triggering definitions, such as what counts as a qualifying illness or disability.
- Choose the two or three riders that address your largest financial risks.
A rider is only worth paying for if it solves a problem you actually have. Price it separately before you add it.
7. How does the insurer handle claims, and what are its financial strength ratings?
A policy is only worth what the insurer pays out. Among the term life insurance questions to ask, this one looks at what your beneficiaries will face after you are gone.
Ask the agent to walk through the claim filing steps, typical processing times, and every document required. Then check the insurer's financial strength rating with AM Best, S&P Global, Moody's, or Fitch. Those ratings signal whether the company can meet its long-term obligations, which may be decades away.
Example: A surviving spouse files a claim online, submits a certified death certificate, and receives payment within a few weeks because the process was documented at purchase.
What to Do Before You Buy
- Confirm the current rating directly on the rating agency's website, not in an advertisement.
- Ask for the average claim payment time and whether claims can be filed electronically.
- Store the policy number and insurer contact details somewhere your beneficiaries can find them.
A strong rating means little if your family cannot figure out how to file. Ask about the claims process as carefully as you compare premiums.
8. What are the free-look and grace periods, and how do I update my beneficiaries?
Some of the most useful policy rights are the ones buyers rarely read about until they need them. Among the term life insurance questions to ask, this one covers three: a free-look window, a grace period, and a way to update who receives the payout.
The free-look period lets you cancel a newly issued policy for a full premium refund within a set number of days, usually 10 to 30 depending on your state. The grace period gives you about 30 extra days to pay a late premium without losing coverage.
A newly married professional reviewed her policy during the free-look window, decided she wanted a higher benefit, and canceled for a full refund before the deadline. She then applied for the amount she actually needed.
Steps to Take Right Away
- Add the free-look deadline to your calendar the day the policy arrives.
- Set up autopay so a missed premium does not push you into the grace period by accident.
- Review beneficiaries after marriage, divorce, or the birth of a child.
- Name contingent beneficiaries in case a primary beneficiary dies first.
A beneficiary form you never updated can override the will you wrote. Check it every few years.
Learn more about how free-look periods work and when to use them.
8 Key Term Life Insurance Questions Compared
| Policy question | 🔄 Complexity | ⚡ Resources required | 📊 Expected outcome | ⭐ Key advantage | 💡 Ideal use case |
|---|---|---|---|---|---|
| Guaranteed renewability and end-of-term options | Moderate: review renewal terms and age limits | Policy wording and written renewal premium schedule | Clear picture of whether coverage can continue and at what cost | Maintains access to coverage if health changes | Coverage needs may continue beyond the original term |
| Conversion option and deadline | Moderate: confirm deadlines, eligible policies, and premiums | Conversion terms and sample premium quote | Understands options for changing to permanent coverage without new underwriting | Can preserve insurability for lifelong needs | Health changes, estate planning, or business protection |
| Level premium period | Low: verify guarantee and term length | Premium schedule and policy guarantee | Predictable costs during the stated level period | Makes household budgeting easier | Families aligning coverage with a mortgage or dependent-care years |
| Contestability period and exclusions | Moderate: review exclusions and disclosure requirements | Policy provisions and application records | Understands early-claim review rules and applicable exclusions | Reduces surprises and encourages accurate disclosure | Anyone evaluating beneficiary protections and claim conditions |
| Medical exam and accelerated underwriting | Moderate: compare underwriting paths and eligibility | Health history; exam or third-party data checks may apply | Estimates approval speed, exam requirements, and possible rate class | Eligible applicants may get coverage faster without an exam | Applicants seeking convenience or a quick decision |
| Available riders and added costs | Moderate: compare rider terms and quotes | Rider descriptions and quotes with and without options | Shows which add-ons fit needs and how they affect premiums | Customizes coverage for specific risks | Families considering disability, illness, or child coverage options |
| Claims handling and financial strength | Moderate: verify procedures and independent ratings | Claims information and current agency ratings | Clarifies claim steps, expected timelines, and insurer strength | Helps beneficiaries prepare and supports confidence in the insurer | Comparing insurers and planning for future beneficiaries |
| Free-look, grace periods, and beneficiaries | Low: check deadlines and update procedures | Policy documents and beneficiary forms | Clarifies cancellation and late-payment windows and how to update beneficiaries | Helps prevent accidental lapses and outdated designations | New policyholders and people experiencing major life changes |
Ask Smart, Buy With Confidence
Two term policies can look nearly identical on a quote page and still behave very differently ten or twenty years later. The details that matter most sit in the policy language, and the eight term life insurance questions to ask below will help you find them.
Your Printable Checklist
Save or print this list before you request quotes:
- Is the policy guaranteed renewable, and what happens when the term ends?
- Does it include a conversion option, and until what age can I use it?
- How long is the level premium period, and can my premium change?
- What is the contestability period, and which exclusions apply in years one and two?
- Do I need a medical exam, and how does accelerated underwriting work?
- Which riders are available, and what do they add to the cost?
- How does the insurer handle claims, and what are its financial strength ratings?
- What are the free-look and grace periods, and how do I update my beneficiaries?
Your Three-Step Action Plan
- Gather at least three quotes with the same coverage amount and term length so the comparison is fair.
- Ask every question in writing. A verbal promise from a sales call rarely holds up during a claim review.
- Compare renewal, conversion, and rider costs side by side. A low starting premium can hide expensive add-ons or a steep jump when the term ends.
The cheapest quote today is not always the cheapest policy by year twenty.
Working through these questions takes an evening, but it can spare your family from surprises when they need the policy most. Coveredly's digital, no-exam term options, with coverage up to $3 million, are one useful place to start comparing.
You do not need to be an insurance expert to buy well. You only need to ask the right questions and keep asking until every answer makes sense.
Ready to put this checklist to work? Compare digital, no-exam term options up to $3 million at Coveredly, where Coveredly makes it easier to line up the numbers that matter. Start with the term life insurance questions to ask, then see how each answer plays out for your family.